Deadline for correcting a tax return / applying for a revision of assessment
As long as it is not deliberate tax evasion, taxpayers may do so within the time limit for revising an assessment, including:
1. After filing the tax return but before receiving the tax demand note;
2. After receiving the tax demand note or paying the tax, request the IRD to correct omissions or errors (omission/error) in the tax return.
Source: Completing Profits Tax Returns, Supplementary Forms and Other Forms
An application for a revision of assessment must be made no later than within 6 years after the end of the year of assessment, or within 6 months after the date of issue of the relevant notice of assessment (whichever is later).
Source: How to claim allowances
Depending on the nature of the error, taxpayers may use different methods to correct an incorrect or omitted tax return.
How to correct errors/omissions discovered while completing a tax return
Corrections for incorrect/omitted tax returns discovered before a notice of assessment is issued
During the interim period after you have filed the tax return but before you receive the tax demand note (notice of assessment), if you discover any omission or error, you may still proactively request the IRD to make a correction.
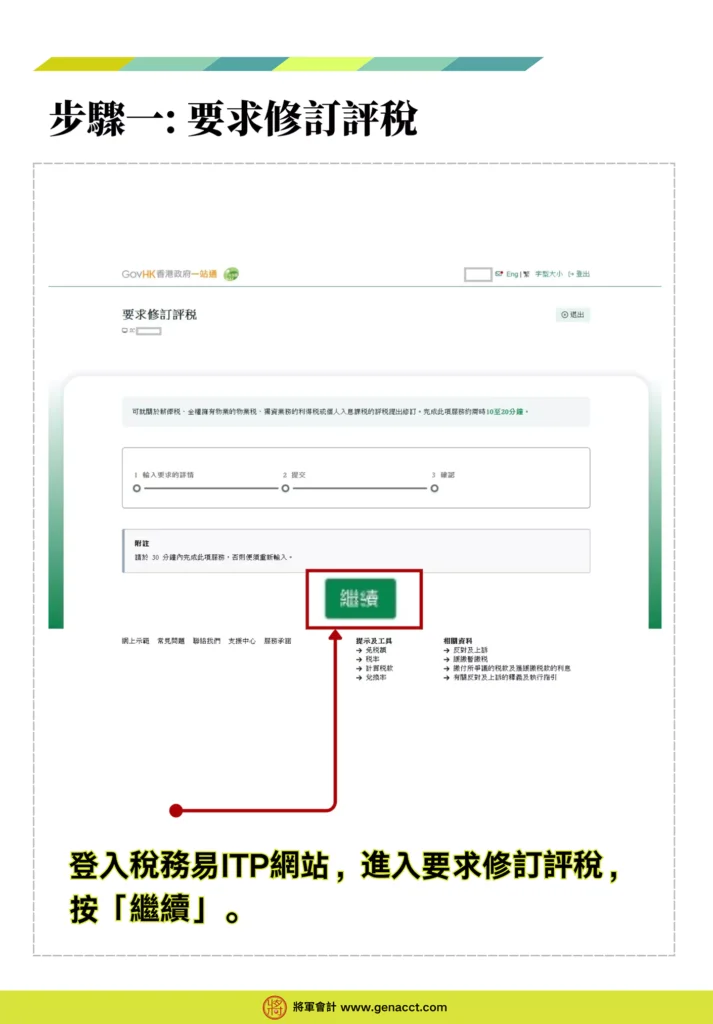
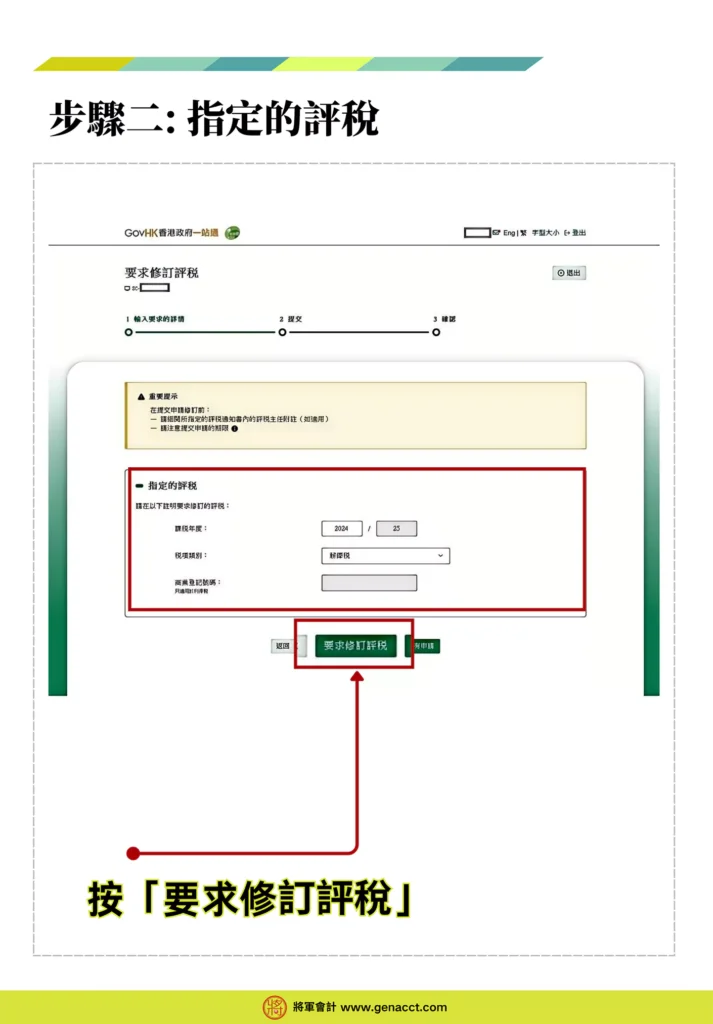
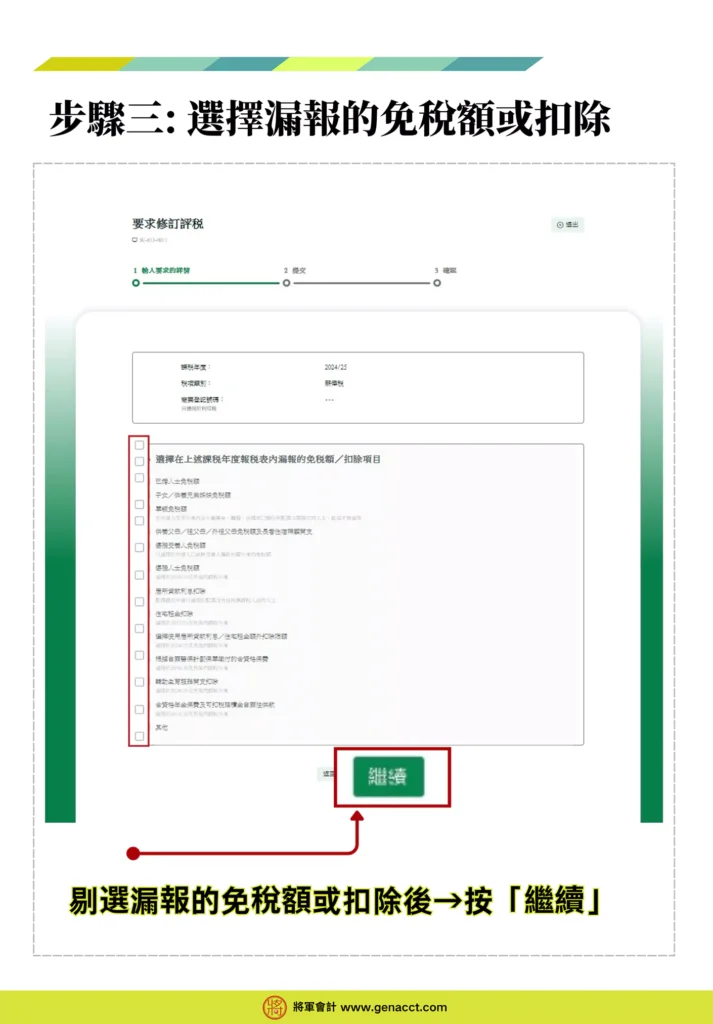
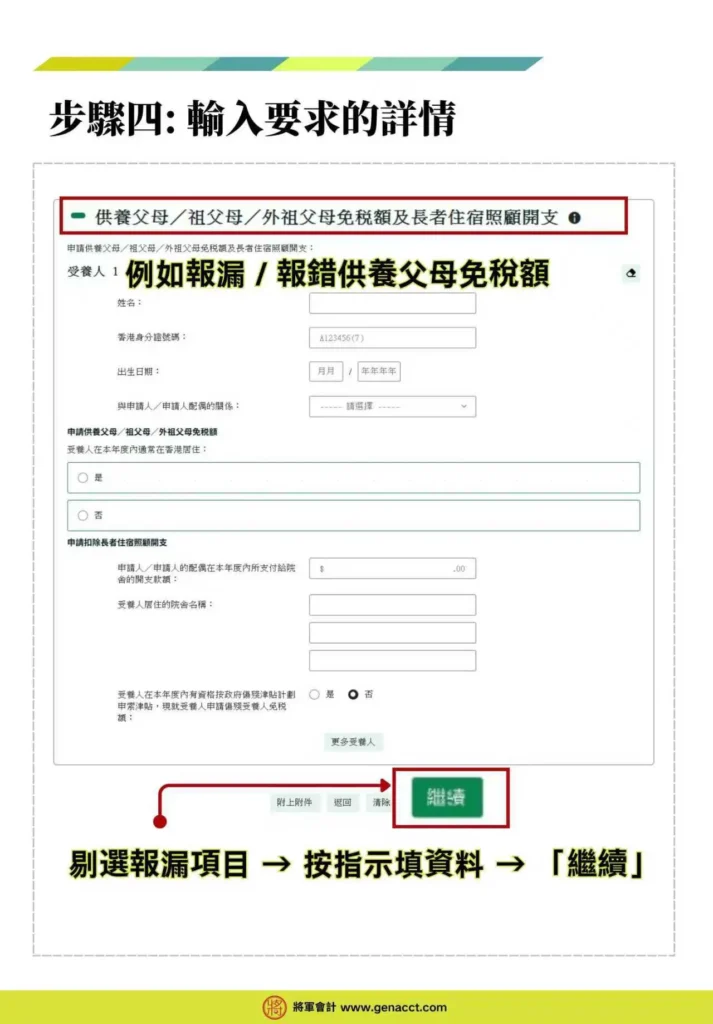
Online correction: You may make corrections via the ITP online platform.
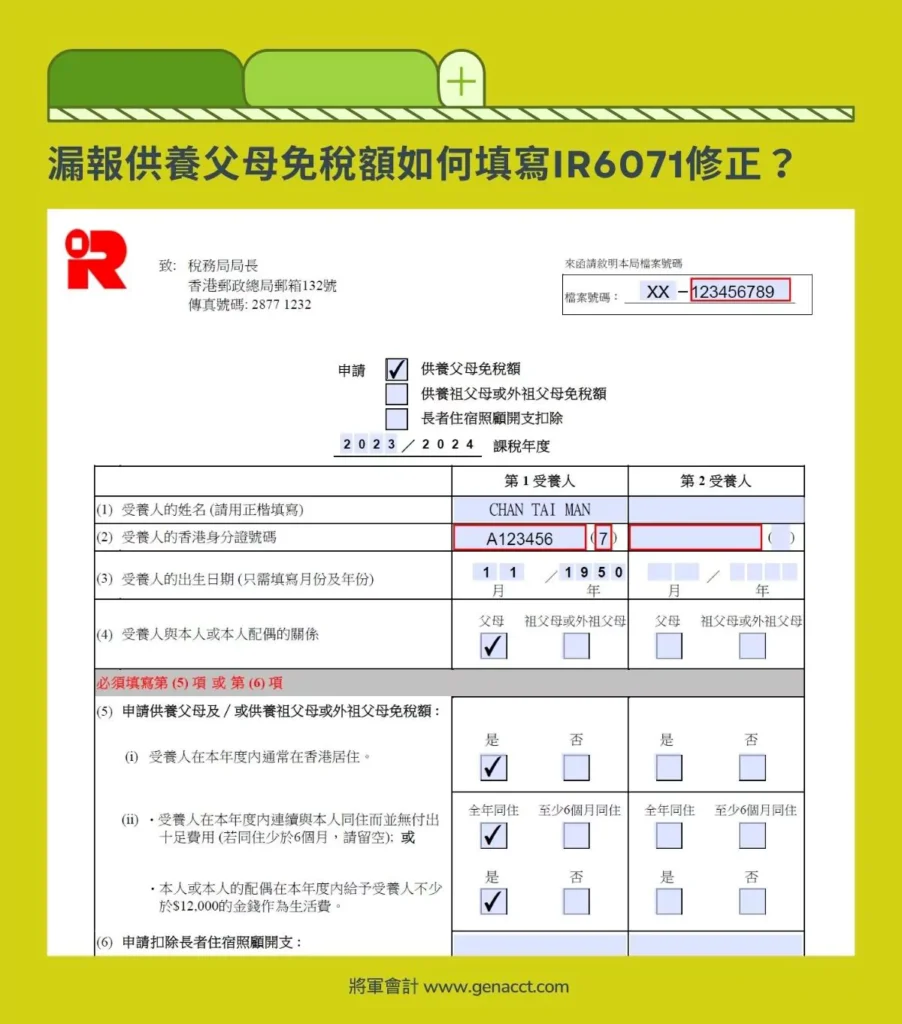
Written correction: You may also notify the IRD in writing. If it involves an omitted allowance—for example, failing to claim the dependent parent allowance—you must complete Form IR6071 to apply to the IRD for the correction. The written notice should clearly state the year of assessment to be corrected, file number, and contact details, so the IRD can understand and process it promptly.
Further reading: Hong Kong Provisional Tax Guide: calculation methods, online application for holdover, and a detailed explanation of the IR1121 process and requirements
Revision of assessment / forms for correcting an incorrect or omitted tax return
IR76C | Correct election for Personal Assessment and claims for deductions and allowances. | Download IR76Cform |
IR6071 | Incorrectly reported or omitted dependent parent allowance, dependent grandparent/grandparent-in-law allowance, or deduction for elderly residential care expenses. | Download IR6071form |
IR6072 | Incorrectly reported or omitted home loan interest / interest paid to produce rental income from property | Download IR6072form |
IR6823 | Incorrectly reported or omitted domestic rent deduction | Download IR6823form |
IR6173 | Incorrectly reported or omitted deduction for qualifying premiums paid under a Voluntary Health Insurance Scheme policy | Download IR6173form |
IR6044 | Incorrectly reported or omitted claims for child allowance and/or dependent brother/sister allowance | Download IR6044form |
After receiving the tax demand note and discovering an incorrect or omitted tax return: formally apply for a “revision of assessment”
After receiving the tax demand note, if the assessment result does not match your expectations, you may formally apply for a “revision of assessment”. This is the most common procedure associated with the “revision of assessment” search intent.
How to apply: You may apply via the ITP online platform, submit Form IR831, or apply in writing to the IRD to correct incorrect information in the tax return.
Time limit: An application for a revision of assessment must be made no later than within 6 years after the end of the year of assessment, or within 6 months after the date of issue of the relevant notice of assessment (whichever is later).
Outcome: If the application is accepted, the IRD will issue a revised notice of assessment, and you only need to pay the revised amount of tax. If you have overpaid, the IRD will refund the excess by cheque.
Further reading: When will the tax refund cheque arrive? Key points on IRD refunds of Profits Tax/Salaries Tax
Only discovered the tax return was incorrect after paying tax
If you only discover the tax return was incorrect after paying tax, you may apply for a revision of assessment in writing or using Form IR831. The IRD allows taxpayers to make corrections due to an incorrect tax return within 6 years after the end of the year of assessment.
If the application is accepted, the IRD will issue a revised notice of assessment and refund the overpaid tax by cheque.
Complete Form IR831, “Notice of Objection / Application for Revision of Assessment”, tick the revision reason that applies to you, and submit the application for revision of assessment to the Commissioner of Inland Revenue by post or fax together with supporting documents. Download IR831form
- Mailing address: P.O. Box 28777, Kowloon Central Post Office, Hong Kong
- Fax number: 28771232
What is the difference between a revision of assessment and an objection to assessment?
Although both “revision of assessment” and “objection to assessment” may use Form IR831, a revision of assessment (Revision) usually refers to a taxpayer proactively discovering an error or omission in their tax return and requesting the IRD to correct it. An objection to assessment (Objection), on the other hand, refers to a taxpayer disagreeing with the assessment decision made by an assessor (e.g., the IRD does not allow a certain deduction or allowance) and lodging an objection to assessment with the Commissioner of Inland Revenue.
This distinction is crucial. If a taxpayer mistakenly treats dissatisfaction with the IRD’s assessment decision as a simple “revision” and misses the 1-month objection deadline, they will lose the legal right to initiate subsequent appeal procedures.
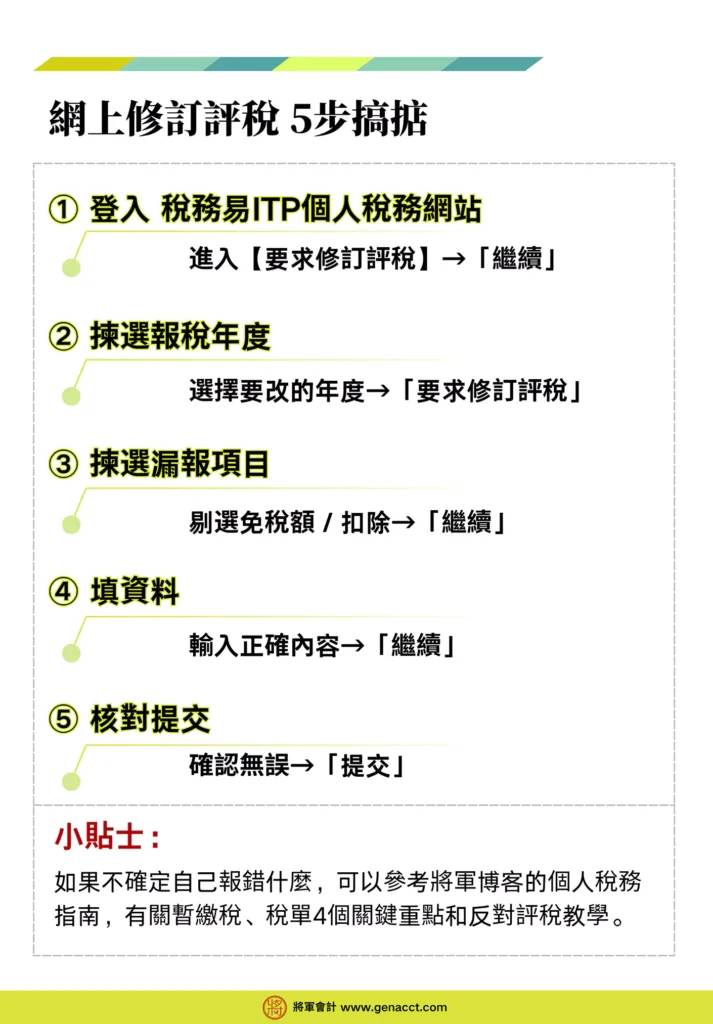
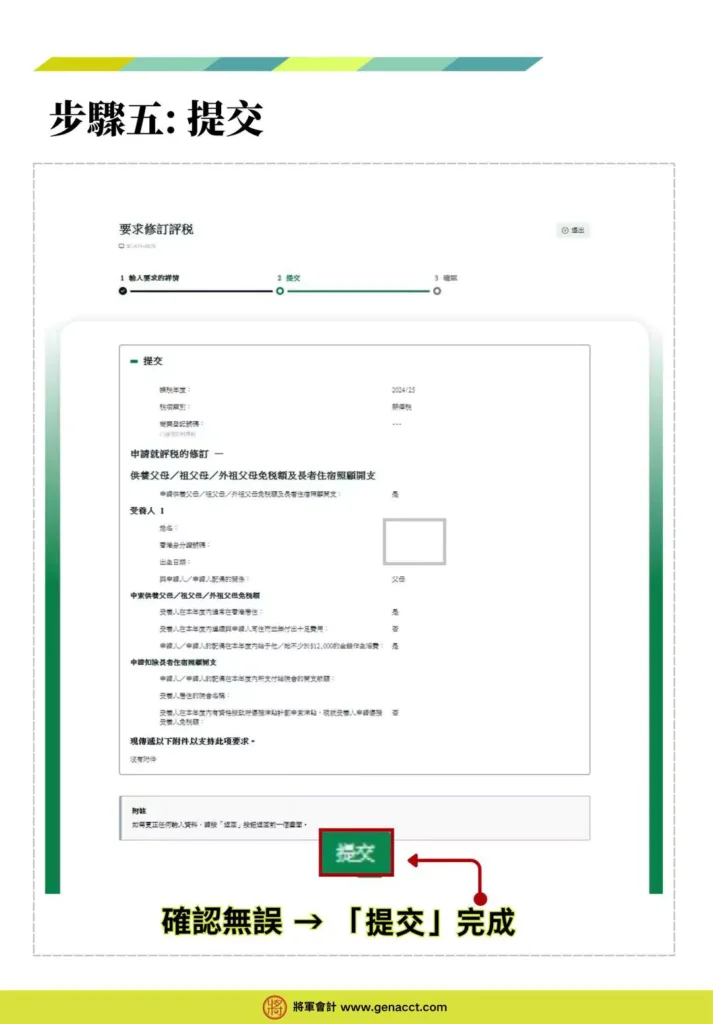
How to correct an incorrect tax return? 5 key steps to apply for a revision of assessment online
In addition to correcting an incorrect tax return via forms, taxpayers may also apply for a revision of assessment online via the Tax Filing Easy Personal Tax website (ITP). For an ITP walkthrough, please refer to another article: Tax Filing Easy Personal Tax website login guide
Correcting an incorrect tax return in writing
How long does a revision of assessment take?
According to the IRD’s service pledges from April 2025 https://www.ird.gov.hk/eng/abo/pam32.htm, 98% of cases will receive a reply to the notice of objection within 12–18 days, and cases will be concluded within 4 months. If a revision of assessment is successful, a cheque refunding any overpaid tax will be issued within 10 working days after the revised notice of assessment is issued.
Frequently Asked Questions
Conclusion
This article explains how to correct errors or omissions in a tax return. If you discover an error after submitting your tax return, you may apply for a revision of assessment before or after the tax demand note is issued. Depending on the circumstances, you will need to complete the relevant form, such as IR76C or IR831, or make corrections via the Tax Filing Easy (ITP) online platform. If the application is successful, the IRD will issue a revised notice of assessment and, where applicable, refund any overpaid tax. Taxpayers should pay tax within the deadline; even if the revision application is still being processed, payment must not be delayed.
General Accounting has been established for over 20 years and provides preliminary consultation on incorrect tax returns. Trust or Company Service Provider licence no.: TC002940. If you have any questions about correcting an omitted tax return, our professional Customer Service Managers can provide free preliminary assistance with enquiries on tax return corrections / revision of assessment.